 We are excited and grateful to be partnering with the National Cooperative Bank as a valued program sponsor.
NCB’s mission is to support and be an advocate for America’s cooperatives and their members, especially in low-income communities, by providing innovative financial and related services.We wanted to be sure that our members and worker co-op supporters have an opportunity to learn more about National Cooperative Bank (NCB), its history, and current services in support of coop businesses and the coop ecosystem.
Check out our brief interview with Casey Fannon, President and CEO of NCB, below.
We know the National Cooperative Bank was founded to support the co-op movement. Can you share a bit about its history and mission?
The National Cooperative Bank (NCB) was founded to meet the financial needs of cooperative organizations owned by the people they serve. Chartered by Congress in 1978, NCB was created to fill a gap in the financial system by providing capital to consumer owned cooperatives that traditional banks often overlooked. Its congressional mandate also emphasized supporting community revitalization and low-income communities.
NCB was privatized in 1981 and is now owned by more than 3,400 cooperative customers who share in the benefits of cooperative ownership.
In 2025 alone, NCB deployed $561.5 million in mission focused loans and investments, with 45% of its portfolio serving low and moderate income communities.
What makes NCB different from other banks?
NCB is the only U.S. bank dedicated to serving cooperatives and member-owned organizations nationwide. Because NCB operates for the benefit of its cooperative members—not outside investors—it can prioritize both doing well and doing good. This structure allows NCB to focus on:
- Affordable housing
- Healthy food systems
- Renewable energy
- Small business growth
- Community-based health care
- Nonprofit organizations
For 46 years, NCB has financed businesses that strengthen local communities.
“Concern for Community” is central to the cooperative way. How does NCB work to meet the development needs of local businesses and the communities they operate in?
NCB is a federally regulated financial institution, while Community Development Financial Institutions (CDFIs) are mission-driven lenders with more flexibility to support early-stage or smaller cooperative projects.
Because of regulatory constraints, NCB cannot always lend directly to startup or small cooperatives. To bridge this gap, NCB partners with CDFIs that specialize in cooperative lending—such as Shared Capital Cooperative, Cooperative Fund of the Northeast, and LEAF.
NCB provides loans, investments, and grants to CDFIs, and can participate, or structure blended deals with CDFIS to expand capital access.
NCB also founded Rochdale Capital, a Community Development Loan Fund designed to help small businesses and cooperatives grow.
How can NCB help worker-owners and aspiring worker-owners grow their businesses?
NCB offers a full suite of banking products tailored to cooperatives, including:
- Real Estate Loans and lines of credit
- Treasury management services
- Deposit products
These tools help cooperatives manage operations, finance growth, and build long-term financial stability.
How does supporting NCB help support the cooperative movement?
Deposits made by cooperatives at NCB directly fuel lending to other cooperatives, strengthening the entire cooperative ecosystem.
NCB embodies Cooperative Principle #6: Cooperation Among Cooperatives. When co-ops bank with NCB, their funds are reinvested into affordable housing, food co-ops, worker co-ops, community facilities, and other cooperative initiatives nationwide.
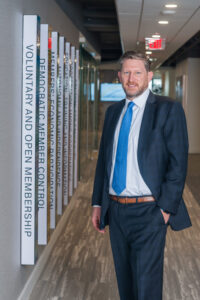
Thank you Casey [pictured left] and the National Cooperative Bank team for supporting the USFWC and sharing this information with our community!
Learn more about the National Cooperative Bank online at https://www.ncb.coop/.
You can also reach out directly to Michael Banish, Vice President, Treasury Management Sales Officer at NCB at mbanish [at] ncb.coop